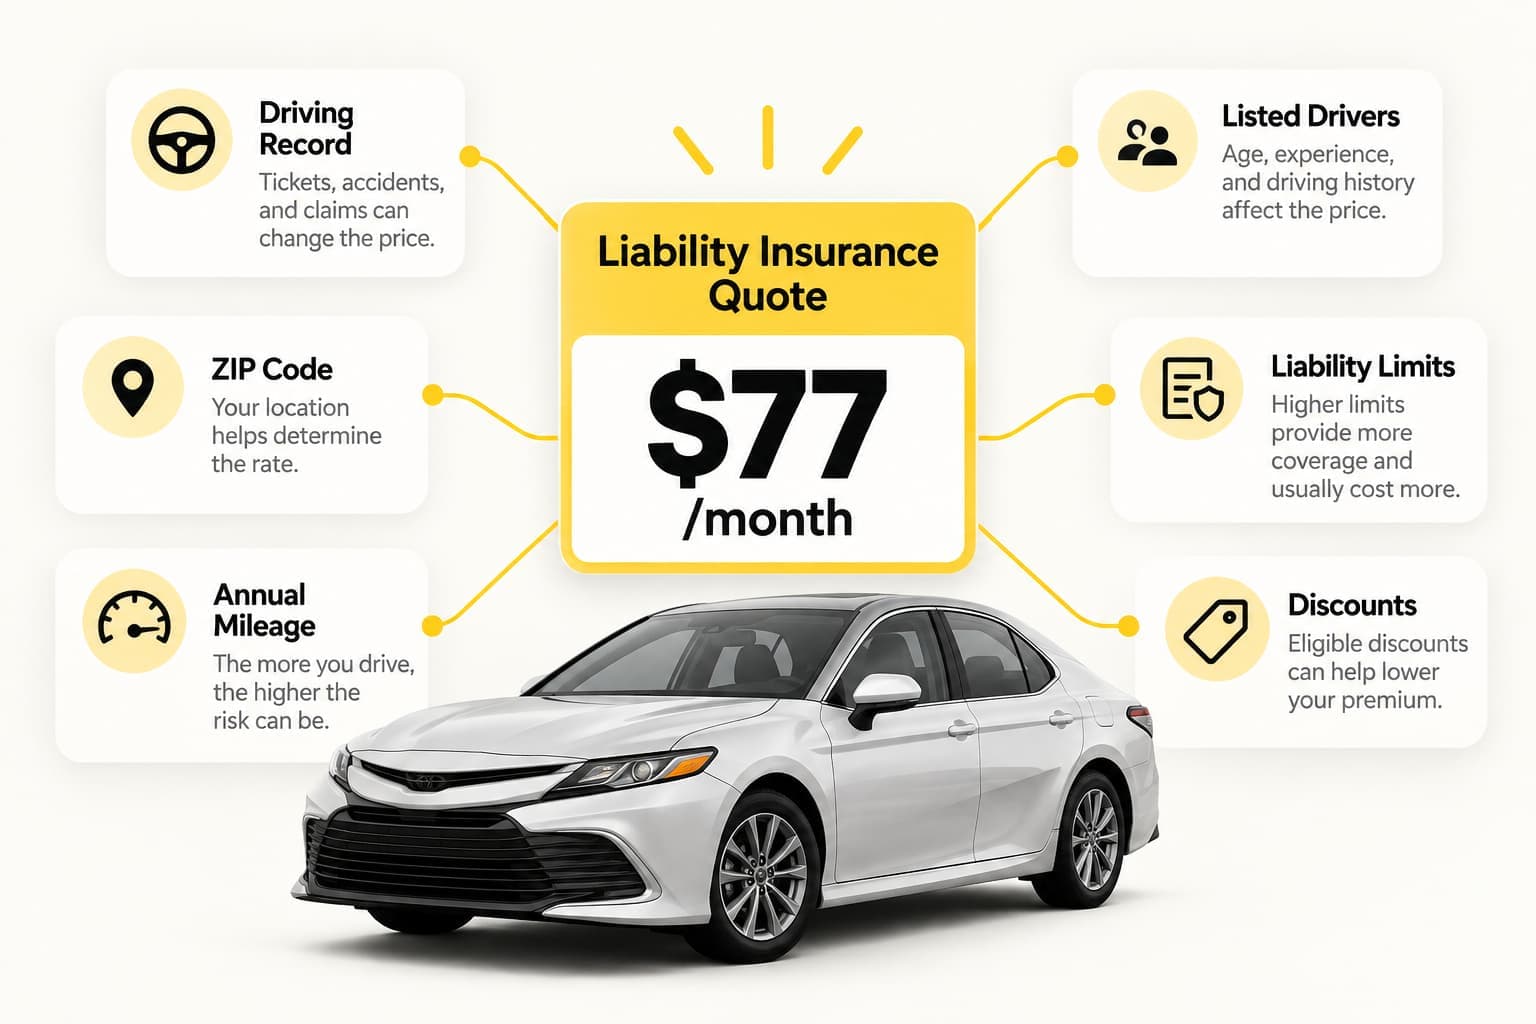
Several factors go into the price of liability car insurance in Oklahoma City. Your driving record, ZIP code, coverage limits, vehicle use, insurance history, and the drivers on the policy are some of the details insurers use when setting a rate.
Understanding those factors makes it easier to compare low cost automobile insurance options and know what you are paying for.
Liability car insurance in Oklahoma City starts with Oklahoma’s required coverage, while the final price reflects the details of the policy and the people insured.
Driving Record
Tickets, at-fault accidents, and claims are part of the driving history insurers review when pricing auto insurance.
A clean recent record can help support a lower rate. Speeding tickets, accidents, and other violations can increase the price.
In Oklahoma, insurers can use the previous three years of driving record history when determining auto insurance premiums.
Where the Vehicle Is Kept
Location is part of the rate.
Insurance companies use the area where the vehicle is normally garaged when calculating a premium. Local accident frequency, traffic, theft, and other loss patterns can all factor into pricing.
That makes ZIP code relevant in a large metro such as Oklahoma City, where traffic and driving patterns can vary from one area to another. Recent car insurance rate data also shows how insurance prices vary across different locations and markets.
Drivers on the Policy
The people listed on the policy also influence the price.
Insurers can consider:
- Age
- Driving experience
- Driving record
- Claims history
- Number of drivers on the policy
Younger drivers often cost more to insure because they have less experience behind the wheel. Adding another driver also brings that person’s driving history into the policy.
Liability Limits
Oklahoma’s minimum liability insurance requirements start at 25/50/25:
- $25,000 for bodily injury per person
- $50,000 for bodily injury per accident
- $25,000 for property damage per accident
Higher liability limits provide more coverage for a covered loss and usually come with a higher premium.
When comparing prices, check the limits first. A 25/50/25 policy and a policy with higher limits represent different levels of coverage.
Vehicle and Mileage
The vehicle remains part of the rating process with liability-only insurance.
Insurers can look at:
- Vehicle type
- Vehicle age
- Annual mileage
- How the vehicle is used
- How often it is driven
A car used for a daily commute around Oklahoma City has different driving exposure than a vehicle used only a few times each week.
Mileage and vehicle use help give the insurer a clearer picture of how often the car is on the road.
Previous Insurance
Insurance history can also influence the price.
Companies may review previous coverage, how long the policy was active, recent lapses, and prior claims.
Continuous prior insurance can help provide a stronger coverage history. A recent lapse gives the insurer a different insurance history to evaluate.
Accurate prior-insurance information also helps produce a more accurate quote from the start.
Credit-Based Insurance Information
Oklahoma allows insurers to use credit-based insurance information as one factor in auto insurance pricing.
An insurance score uses information from a person’s credit history to help evaluate insurance risk. It works alongside other factors such as driving history, location, vehicle use, and coverage selections.
The weight given to each factor varies by insurance company.
Discounts
Discounts can bring the final premium down.
Available discounts vary by insurer and policy. Cheapest Auto Insurance offers eligible discounts that can include:
- Multi-car
- Proof of prior insurance
- Homeowners
- Renters bundle
- AutoPay
- Paperless billing
- Paid in full
- Defensive driving
- Military
- First responder
- Good driving
Checking available discounts is especially useful when comparing similar liability policies.
Why Prices Vary by Insurance Company
Each insurance company develops its own rates, underwriting guidelines, and discount structure.
A driving record that receives one price from one company can receive another price elsewhere. The same applies to ZIP code, prior insurance, vehicle use, and other rating details.
This is one reason comparing liability quotes can be useful when shopping in Oklahoma City.
Compare the Coverage Along With the Price
A useful price comparison starts with similar policy details.
Check that each quote uses:
- The same liability limits
- The same drivers
- The same vehicle
- The same garaging address
- Similar optional coverages
For example, a lower-priced policy with 25/50/25 limits is a different product from a policy with higher liability limits.
Matching the main details makes the price comparison much clearer.
Frequently Asked Questions
What information affects a liability insurance quote the most?
Driving history, age, garaging location, listed drivers, liability limits, prior insurance, vehicle use, and available discounts are all part of the rating process. The weight given to each factor varies by insurance company.
Can prior insurance help lower the cost of liability coverage?
Prior insurance can influence the rate. A consistent coverage history gives insurers more information about your insurance background, and some companies offer discounts for proof of prior coverage.
Will adding another driver change my liability insurance price?
Yes. Adding a driver brings that person’s age, experience, driving record, and claims history into the policy, which can raise or lower the final premium.
Does the car I drive matter if I only have liability insurance?
Yes. Vehicle type, age, mileage, and how the car is used can still be part of the rating process even when collision and comprehensive coverage are left off the policy.
Why did my liability insurance quote change from the last time I checked?
A new driving record entry, address change, different vehicle use, updated insurance history, new drivers, revised coverage limits, or an insurer rate update can all affect a new quote.
How can I compare liability insurance prices accurately?
Use the same drivers, vehicle, address, liability limits, and optional coverages for each quote. That keeps the comparison focused on the actual price difference between similar policies.