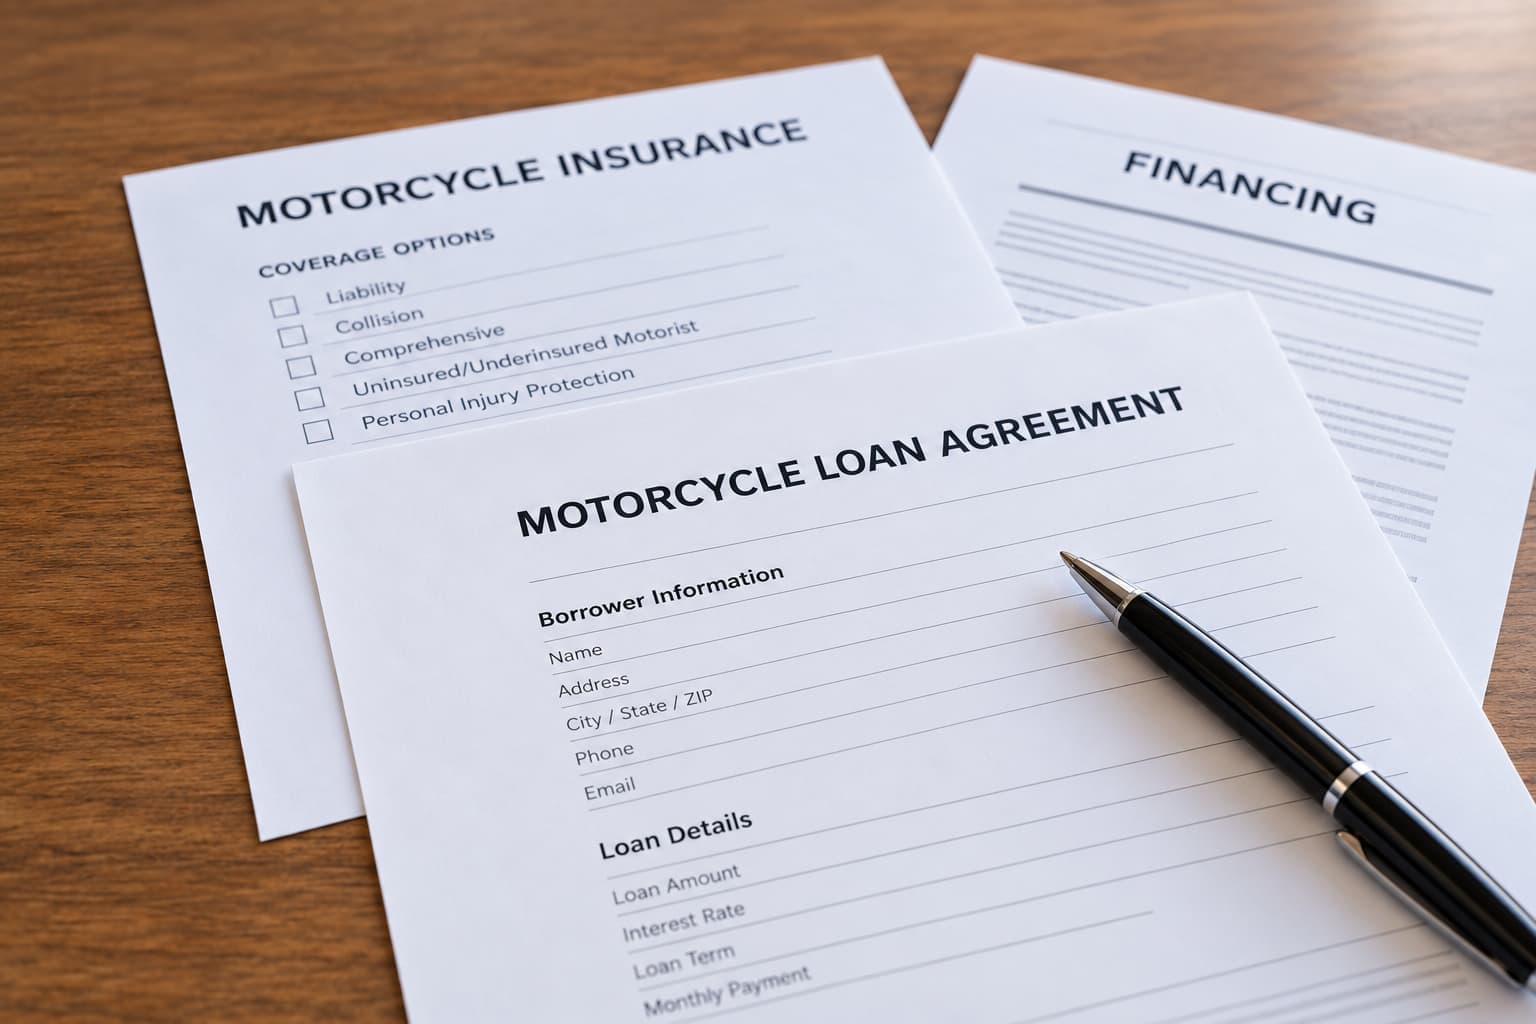
If you are financing a motorcycle in Oklahoma City, liability insurance is usually only part of what you need. Oklahoma sets the minimum insurance requirements for riding legally, while your lender can require additional coverage on the motorcycle until the loan is paid off.
For most financed motorcycles, that usually means carrying:
- Liability
- Collision
- Comprehensive
- A deductible that meets the lender’s requirements
- The lender listed on the policy when required
The exact requirements are written into your financing agreement, so it is worth checking those before setting up the policy.
Oklahoma’s Requirement and Your Lender’s Requirement Are Different
This is where people can get confused.
Oklahoma decides what coverage you need to legally operate the motorcycle.
Your lender decides what coverage you need to keep while there is still a balance on the loan.
So while liability-only insurance may meet Oklahoma’s legal requirement, it may not meet the requirements of your financing agreement.
The lender usually wants the motorcycle itself protected too, not just the damage you could cause to someone else. If required coverage lapses, the lender may also have the right to purchase force-placed insurance and charge the cost back to the borrower.
What Coverage Is Usually Required on a Financed Motorcycle?
A financed motorcycle will generally need liability, collision, and comprehensive coverage.
Lenders may require collision and comprehensive coverage in addition to the insurance required by the state because those coverages help protect the motorcycle itself.
Liability
Liability coverage is the part Oklahoma requires.
It covers certain injuries or property damage you cause to someone else in an accident. It does not normally cover damage to your own motorcycle.
That is why liability by itself is usually not enough on a financed bike.
Collision
Collision coverage applies to damage to your motorcycle from a crash.
That can include hitting another vehicle, striking an object, or certain single-bike accidents.
If there is still a loan on the motorcycle, the lender will usually require collision coverage because the bike still has financial value tied to the loan.
Comprehensive
Comprehensive covers certain damage that is not caused by a crash.
That can include things like:
- Theft
- Hail
- Fire
- Vandalism
- Wind damage
- Falling objects
This matters even when the motorcycle is parked.
For example, a bike sitting outside an Oklahoma City apartment or home can still be damaged by hail, wind, theft, or vandalism without ever being involved in a collision.
Does a Financed Motorcycle Need Full Coverage?
In most cases, yes.
“Full coverage” is not an official policy type, but people usually use the term to mean:
Liability + Collision + Comprehensive
Those are also the main coverages a lender is likely to require on a financed motorcycle.
The part to watch is that “full coverage” can mean different things to different people.
Your lender may have its own requirements for deductibles or coverage limits, so it is better to look at the financing paperwork than simply ask for “full coverage.”
If you are comparing motorcycle insurance in Oklahoma City, use the actual lender requirements so you are comparing policies that would work for the loan.
Does the Lender Need to Be Listed on the Policy?
Usually.
If a motorcycle is financed, the lender will often need to be listed on the insurance policy as the lienholder or loss payee.
That tells the insurance company that someone else has a financial interest in the motorcycle.
The easiest way to avoid mistakes is to use the lender information exactly as it appears on your financing paperwork.
That may include:
- The lender’s legal name
- Mailing address
- Loan or account information if requested
This is a small detail, but entering it incorrectly can mean having to update the policy later.
Can the Lender Limit Your Deductible?
Yes.
You may not be able to choose any deductible you want on a financed motorcycle.
A higher deductible can sometimes lower the premium, but your lender may set a maximum amount for collision or comprehensive coverage.
For example, if the financing agreement only allows a deductible up to a certain amount, choosing something higher would not meet the loan requirements.
Before deciding on a deductible, check what the lender allows.
Can You Carry Liability Only on a Financed Motorcycle?
Usually not.
Liability-only insurance may keep you legal under Oklahoma law, but it generally will not satisfy a lender that requires collision and comprehensive coverage.
That is an important distinction when shopping for insurance.
If the motorcycle is financed, comparing liability-only prices may not tell you much because you may not actually be allowed to carry liability-only coverage under the loan agreement.
What Happens When the Motorcycle Is Paid Off?
Once the loan is paid off, the lender no longer controls the insurance requirements.
At that point, you can decide whether you still want collision and comprehensive coverage.
Some riders keep both. Others decide to reduce coverage as the motorcycle gets older or loses value.
The right choice depends on the bike, what it is worth, and how much you would be comfortable paying out of pocket if it were damaged or stolen.
Oklahoma’s liability requirement still applies if you are riding the motorcycle on public roads.
What Should You Have Ready Before Setting Up Coverage?
For a financed motorcycle, it helps to have a few things ready before starting the policy:
- The motorcycle’s VIN
- Year, make, and model
- Your lender’s information
- Required deductibles
- Any coverage limits listed in the loan agreement
That makes it easier to set up the policy correctly the first time.
When a motorcycle is financed, the coverage needs to meet both Oklahoma’s insurance requirements and the terms set by your lender.
If you’re financing a motorcycle in Oklahoma City, Cheapest Auto Insurance can help you compare motorcycle insurance options based on the coverage and deductible requirements of your loan.